A church may have a capable treasurer, bookkeeper, administrator, or volunteer who keeps the accounting records and prepares the bank reconciliation. The question is not whether one particular church office is supposed to do the reconciliation. The more important question is whether the way the work is divided gives one person too much control over the entire process.
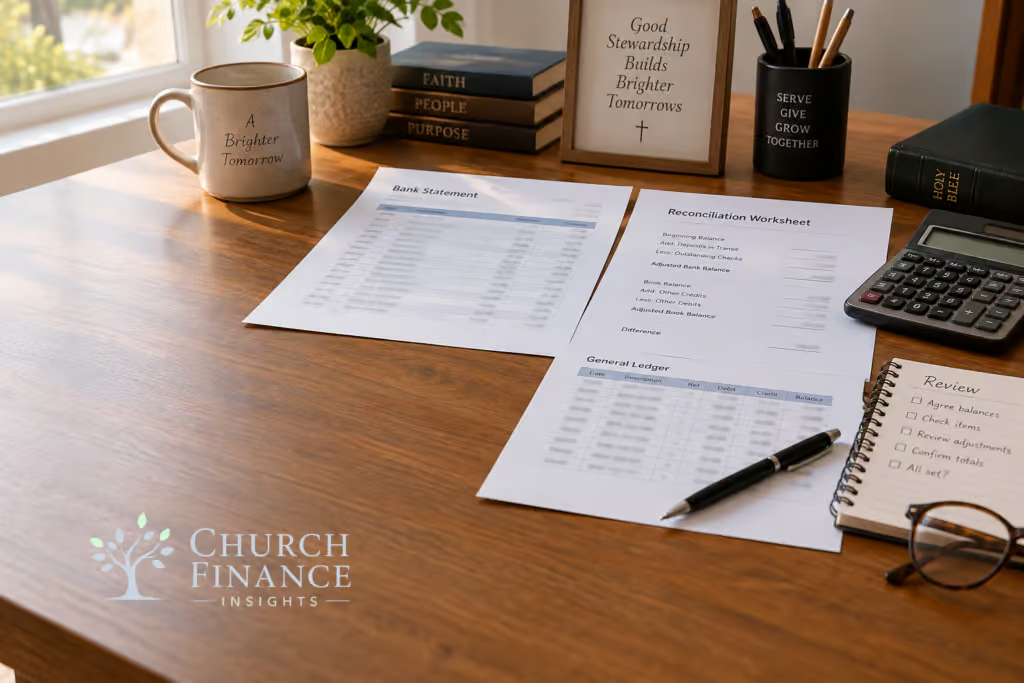
A bank reconciliation compares the church’s accounting records with the bank’s records and explains the differences. It can uncover recording mistakes, missing bank fees, duplicate entries, old outstanding checks, deposits that have not cleared, and transactions that need follow-up. It is also an important part of the church’s financial controls because unusual activity is harder to conceal when someone else is looking at independent bank information.
That matters in churches. The World Christian Database estimates that approximately $70 billion is embezzled from the Church worldwide every year. Good controls do not guarantee that fraud will never happen, but they can reduce the opportunity for misuse, make concealment more difficult, and increase the chance that something unusual will be noticed.
Start With the Process, Not the Title
When I teach segregation of duties, I ask churches to look at four parts of the financial process:
Who approves the transaction?
Who has access to or can move the money?
Who records the transaction?
Who reconciles the records to the bank?
Ideally, those responsibilities are separated enough that one person cannot control a transaction from beginning to end and then determine for themselves whether everything is correct. That does not mean four different people are always required. Many churches simply do not have the staff or volunteer capacity to divide every task that way, so the important question is where responsibilities overlap and what risk that overlap creates.
For example, a bookkeeper may both enter transactions and prepare the bank reconciliation because that person is the only one who knows the accounting software. That is not the same risk as allowing one person to approve payments, move money, record the transactions, prepare the reconciliation, and be the only person who sees the bank activity. There is no universal accounting rule assigning the reconciliation to a particular church office, although a church policy, denominational requirement, grant, lender, or other applicable rule may be more specific. The title does not tell you whether the process is well controlled; the combination of duties does.
Who Should Prepare the Reconciliation?
The person preparing the reconciliation should understand the church’s accounting records well enough to compare them with the bank’s information, identify legitimate timing differences, investigate unexplained differences, and make or request appropriate corrections. Depending on the church, that could be a treasurer, bookkeeper, administrator, financially knowledgeable volunteer, or outside bookkeeping provider.
Where possible, the preparer should not also control every other part of the cash process. The church should pay particular attention when the same person can approve a payment, initiate or sign it, change the accounting record, and then reconcile the account afterward. That concentration creates an opportunity not only for intentional misuse but also for ordinary mistakes to go unnoticed. Self-review cannot provide the same independent check as another set of eyes.
Who Should Review the Reconciliation?
The reviewer should ordinarily be someone other than the person who prepared the reconciliation. Again, the office title is not the deciding factor. A treasurer, finance chair, finance committee member, board member, administrator, pastor, or another financially knowledgeable volunteer might be appropriate if that person is sufficiently removed from the transactions and records being reviewed.
The reviewer does not need to redo the entire reconciliation, but reviewing should mean more than signing or initialing the last page. The reviewer should be able to see the completed reconciliation and reliable information that came from the bank. The review should be sufficient to notice whether the reconciled balance agrees with the accounting records and whether anything deserves explanation, including old outstanding checks, deposits that remain outstanding, unusual transfers, ACH withdrawals, returned items, unexpected fees, manual adjustments, or other transactions that do not look ordinary for the church. The reviewer also needs to know what happened when a question was raised; an unexplained item should not disappear simply because the next month arrived.
Independent access to bank information makes this review stronger. Years ago, churches were often advised to have an unopened bank statement sent to someone other than the bookkeeper. The underlying principle still matters, but the paper procedure is no longer the only way to accomplish it. A reviewer might have read-only online access, download the statement directly, receive bank alerts, or otherwise obtain bank-originated information without depending entirely on what the preparer chooses to provide.
When You Cannot Separate Every Duty, Close the Window
Best practice still matters even when a church cannot achieve the ideal arrangement. If one person must perform two duties that would preferably be separated, identify the window that remains open and ask what can be added to close it as much as possible.
If the bookkeeper also prepares the reconciliation, another leader might receive the bank statement directly and review the reconciliation. If one person has significant online banking access, another leader might receive transaction alerts. If a person must initiate certain transfers, selected transactions might require a second approval. A finance committee or outside accountant might periodically review areas that cannot be separated internally. These are not interchangeable solutions, and they do not eliminate risk; the point is to respond deliberately to the risk created by the duties that must remain together.
This is particularly important in smaller churches. A control that requires more volunteers than the church can realistically recruit is not a workable control. But limited staffing should not mean that one trusted person operates without meaningful oversight. The church can still decide where a second set of eyes matters most.
Controls Protect People as Well as Money
Churches sometimes resist financial controls because leaders do not want faithful volunteers or staff to feel distrusted. That concern is understandable, but good controls should not depend on suspicion. Clear procedures protect the person handling the money as well as the church. When responsibilities are defined, another person reviews the work, and reliable records are available, a treasurer or bookkeeper does not have to carry the full burden of proving that everything was handled properly.
The same controls also make misconduct harder to conceal. A reconciliation will not prove that every transaction was authorized, and an independent review does not prove that fraud is absent. Neither is an audit. They are parts of a larger system of accountability.
So who should reconcile the church bank account? A capable person whose other responsibilities do not give them unchecked control over the entire process. Who should review it? Someone else who can understand what they are seeing, obtain reliable bank information, ask questions, and make sure unusual items are resolved. The goal is not to reproduce an ideal organizational chart. It is to make sure no one person can control the money, the records, and the explanation without another person meaningfully looking.
Sources
World Christian Database. Gina A. Zurlo, ed., Status of Global Christianity, 2026, in the Context of 1900–2075. The table reports approximately $70 billion annually in worldwide embezzlement of Christian monies; the methodological note defines the measure as amounts embezzled by top custodians of Christian monies. Accessed 2026-09-15.
https://dev.worldchristiandatabase.org/static/downloads/Status-of-Global-Christianity-2026.2b54be19fc0c.pdf
Committee of Sponsoring Organizations of the Treadway Commission. Internal Control—Integrated Framework, 2013, including the Executive Summary and Principle 10. Supports reconciliation as a control activity, segregation of duties, and development of alternative controls when full segregation is impractical. Accessed 2026-09-15.
https://www.coso.org/guidance-on-ic
U.S. Government Accountability Office. Standards for Internal Control in the Federal Government, 2025 revision, effective beginning with fiscal year 2026. Used as a current governmental articulation of internal-control design, preventive and detective controls, and risk-responsive oversight. Its requirements govern federal agencies; churches may use the framework voluntarily but are not subject to it merely because it is cited here. Accessed 2026-09-15.
https://www.gao.gov/greenbook
Financial Accounting Standards Board. Standards. FASB identifies its Accounting Standards Codification as the single official source of authoritative nongovernmental U.S. GAAP. Consulted to preserve the distinction between financial-reporting standards and operational role assignments; this article does not present bank-reconciliation staffing as a GAAP mandate. Accessed 2026-09-15.
https://www.fasb.org/standards
AICPA & CIMA. AICPA SASs — Currently Effective, current through August 2026. Used to preserve the distinction between an internal reconciliation review and an audit conducted under professional auditing standards. Accessed 2026-09-15.
https://www.aicpa-cima.com/resources/download/aicpa-statements-on-auditing-standards-currently-effective/
Evangelical Council for Financial Accountability. ECFA Certification Application for Churches. The application asks church applicants about reconciliation timeliness and the positions responsible for cash-handling and reconciliation functions. It is used only as a church-specific accountability example, not as a rule applying to every church. Accessed 2026-09-15.
https://www.ecfa.org/PDF/Offline-Apply-Church.pdf
Grace Communion International. Financial Management Manual, January 2025. Used as a church-specific implementation example concerning bank reconciliation and financial-control review. Its procedures apply within its own denominational context and are not presented as universal church requirements. Accessed 2026-09-15.
https://online.gci.org/GCICommon/Manuals/Financial%20Management%20Manual.pdf